


How to Protect Your Injury Settlement Money in California
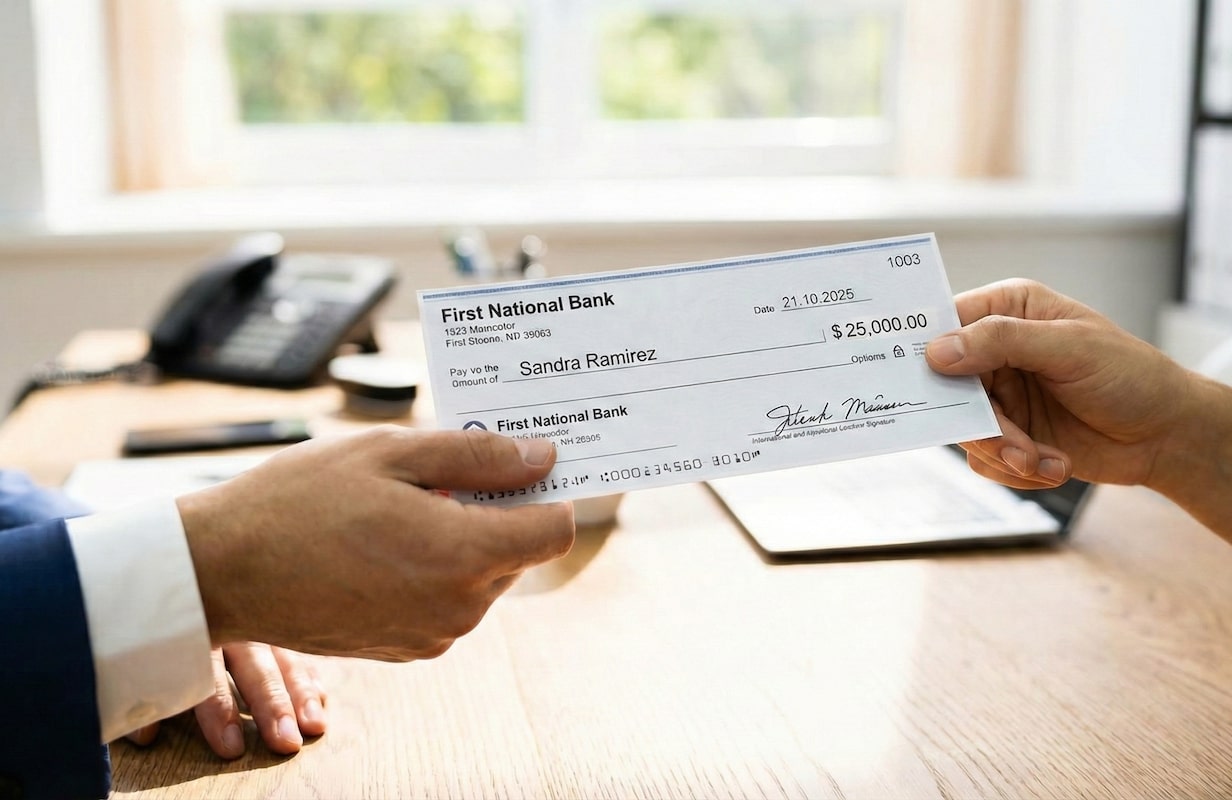
You just got a settlement check. Maybe it’s $150,000. Maybe it’s $1.2 million. Either way, you’re holding more money than you’ve ever had at once, and everyone suddenly has opinions about what you should do with it.
Here’s the problem nobody tells you: a significant number of people who receive lump-sum settlements spend everything within a few years. A MetLife study found that 1 in 5 lump-sum recipients exhaust their entire payout within five and a half years. Another 35% feared they’d run out soon.
Your settlement isn’t just money. It’s supposed to cover medical bills, lost wages, and care you might need for decades. Losing it isn’t an option. So let’s talk about how to actually protect it.
要点
- California law already protects much of your settlement from creditors. Personal injury damages are exempt from collection to the extent needed for your support, and the state’s homestead exemption now shields $300,000 to $600,000+ in home equity.
- Most personal injury compensation is completely tax-free. Damages for physical injuries don’t count as income under IRS rules. But punitive damages and investment earnings are taxable.
- Structured settlements can protect you from yourself. Record numbers of plaintiffs are choosing periodic payments over lump sums. In 2024, $9.8 billion went into structured settlements, a 58% increase from 2022.
- California doesn’t recognize self-settled asset protection trusts. If you create a trust for your own benefit, creditors can still reach those assets. Out-of-state trusts won’t save you either.
What Does “Protecting” Your Settlement Actually Mean?
Protection isn’t one thing. It’s several.
There’s protection from creditors and lawsuits. Protection from taxes eating into your compensation. Protection from family members who suddenly need loans. And honestly, protection from your own spending decisions.
Most people only think about one of these. They open a savings account and call it done. Meanwhile, the other vulnerabilities sit there waiting.
California’s Built-In Protections for Settlements
California recently upgraded its asset protection laws. If you’re a resident, you have some advantages.
The homestead exemption now protects a minimum of $300,000 in home equity from judgment creditors, scaling up to roughly $600,000 or more in high-cost counties. These amounts adjust annually for inflation. So if you use settlement money to pay down your mortgage or buy a home, that equity is largely shielded.
Personal injury damages get special treatment. Under California law, your settlement is exempt from creditors to the extent you need it for support. Courts consider factors such as your medical expenses, earning capacity, dependents, and long-term care needs. A catastrophic injury victim who needs the entire settlement for lifetime care? A court won’t let creditors take it.
Bank accounts have a baseline protection. Since 2020, California law requires that debt collectors leave at least $1,724 (adjusted for inflation) in your bank account. They can’t completely clean you out anymore.
These protections are automatic. You don’t have to do anything special to claim them. But you do need to understand they exist, so you don’t panic and make bad decisions when a creditor comes knocking.
Why Structured Settlements Are Making a Comeback
Here’s something interesting. More plaintiffs than ever are choosing to receive their money in periodic payments rather than a single lump sum.
Why? Because a lump sum is hard to manage. People underestimate how long the money needs to last. They buy cars, help relatives, and invest in a cousin’s business venture. Five years later, they’re broke, and their injuries are still there.
A structured settlement forces discipline. You get payments monthly, quarterly, or annually for years or decades. You literally cannot blow through the principal because you never have access to it all at once.
There’s also a tax advantage. For physical injury cases, the growth of the investment in a structured settlement is completely tax-free. If you took a lump sum and invested it yourself, you’d pay taxes on the earnings every year. With a structure, you don’t.
The downside? Less flexibility. If you need a large sum for an emergency, you can’t just withdraw it. Some people sell their future payments to factoring companies at steep discounts, which defeats the whole purpose.
What About Trusts and LLCs?
This is where it gets complicated. And where many people get bad advice.
California does not recognize self-settled asset protection trusts. Some states, like Nevada and Delaware, let you create a trust for your own benefit that creditors can’t touch. California isn’t one of them. If you’re a California resident and you put money in a Nevada trust, California courts will likely let your creditors reach it anyway.
Trusts for other people do work. If you create an irrevocable trust for your children or spouse (not yourself), those assets are generally protected from your creditors. The catch: you’re giving the money away. You can’t take it back if you need it.
LLCs and family limited partnerships can add a layer of protection through something called “charging order” rules. A creditor who gets a judgment against you can’t simply seize LLC assets. They can only get a lien on distributions. This creates a negotiating advantage and can discourage creditors from pursuing collection aggressively.
But LLCs aren’t bulletproof in California. Single-member LLCs are weaker than multi-member ones. And you’ll still pay California’s $800 annual franchise tax.
Offshore trusts offer the strongest theoretical protection but come with serious drawbacks: they cost $20,000 to $50,000 to set up, require extensive IRS reporting, and U.S. courts can hold you in contempt if you refuse to bring the money back. These are really only appropriate for very large settlements with specific risk profiles.
The Tax Situation Is Actually Good News
Here’s something that surprises most people: your personal injury settlement probably isn’t taxed at all.
Under federal law, damages received for physical injuries are excluded from income. Pain and suffering, medical expenses, lost wages from the injury, all of it. Tax-free. California follows the same rule.
The exceptions matter, though:
- Punitive damages are fully taxable as ordinary income
- Interest on delayed payments is taxable
- Investment earnings on your settlement after you receive it are taxable
So if you got a $500,000 settlement and $50,000 of that was punitive damages, you’ll owe income tax on the $50,000. At combined federal and California rates, that could be close to 50%. People who don’t plan for this end up with IRS problems.
Practical Steps to Take Now
If you’ve received or are expecting a settlement, here’s what actually matters:
Don’t make major financial decisions immediately. The first 90 days after receiving a large sum are when people make the worst mistakes. Park the money somewhere safe and boring while you plan.
Understand what’s taxable. Review your settlement agreement to see how damages were allocated. If there’s a punitive or interest component, set aside money for taxes before doing anything else.
Consider your debt situation. If you have existing creditors, understand which protections apply to your settlement before you start spending or moving money around.
Get professional help. This isn’t a DIY situation. You need a financial advisor who understands settlement money (not just general wealth management) and possibly an attorney for asset protection planning.
Think about structure. If you haven’t received the money yet, seriously consider whether periodic payments make more sense than a lump sum for your situation.
The goal isn’t to hide your money or play games with creditors. It’s to make sure the compensation you received for your injuries actually serves its purpose: taking care of you for as long as you need it.
If you’re expecting a settlement or have questions about protecting compensation you’ve already received, DK Law can help you understand your options. 联系我们获取免费咨询.
DK 一路走来


从您的案件到赔偿,我们全程为您服务。
安排免费咨询
在专家法律咨询处获得专业法律建议 零成本。.
在DK Law,我们与您同在—— 全程都在。.
立即与我们的专家免费咨询!

事故发生后时间很重要
事故发生后越早与律师联系,你的索赔就越有胜算。及早行动有助于保全证据并维护你的权益。.
无需支付费用即可获得法律援助 | 24×7全天候服务