


Car Injury Settlement Calculator | California
Estimate a California car injury claim, then learn what the available insurance may actually pay.
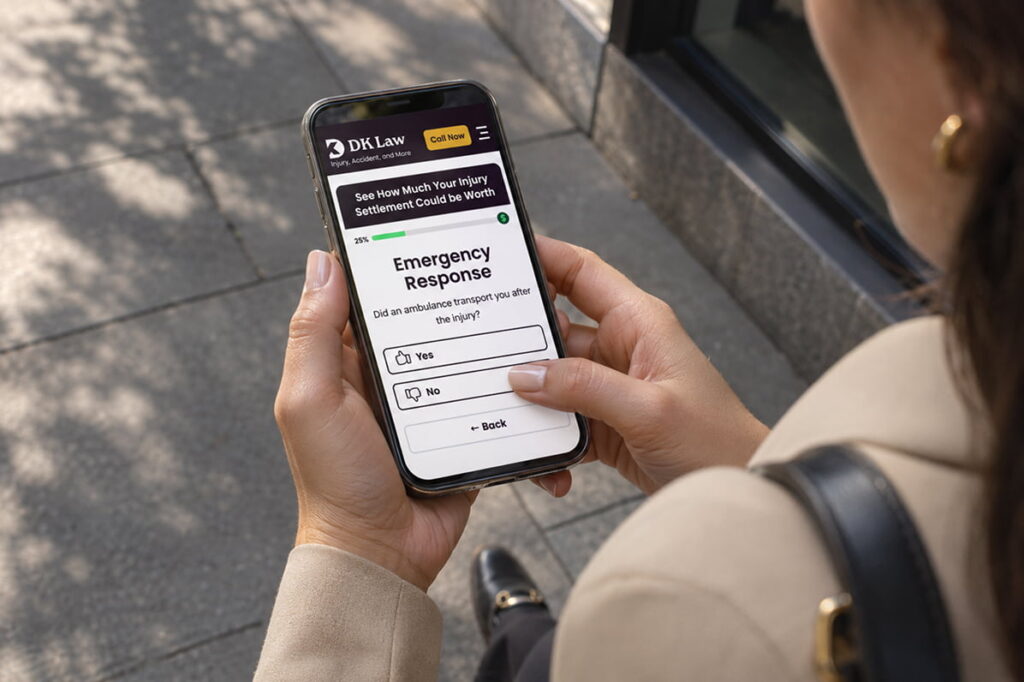
자신의 부상 보상금이 얼마나 될 수 있는지 확인해 보세요.
시작하기
어떤 종류의 사고에 연루되었나요?
유효 자동차 보험
사고 당시 유효한 자동차 보험이 있었나요?
응급 대응
부상 후 구급차가 당신을 이송했나요?
고용 정보
부상 당시의 직업 상태를 가장 잘 묘사하는 것은 무엇인가?
경제적 피해
자신의 재정적 손실을 계산하세요.
고통과 고난
상해와 그 영향에 가장 적합한 옵션을 선택하세요.
책임 평가
사고의 어느 부분이 당신의 잘못이라고 생각하는지 기재하세요.
책임이 없다
추정 합의금 가치
참고: 이는 추정치일 뿐입니다.
추정 총 보상
$0
경제적 피해
통증 및 고통 –
세부 계산 내역
경제적 피해
고통과 고난
책임 조정
이 계산기는 캘리포니아의 개인 상해 사건에서 일반적으로 사용되는 정산 공식에 기반한 추정치만을 제공합니다. 각 사건은 고유하며, 실제 정산 금액은 특정 사실, 증거 품질, 보험 보장 범위, 협상 역학에 따라 크게 달라질 수 있습니다. 이 도구는 법률적인 조언이 아닙니다. 귀하의 사건에 대한 정확한 평가를 위해서는 자격을 갖춘 캘리포니아 개인 상해 변호사와 상담하시기 바랍니다.
What a car injury claim is worth and what it can actually collect are two separate questions. The calculator answers the first one. The sections underneath answer the second, which in California comes down to whose policy applies, how much coverage exists on it, and whether you were insured yourself on the day of the crash.
핵심 요약
- California drivers have carried at least $30,000 per person and $60,000 per accident in bodily injury coverage since January 1, 2025. Those figures will rise again in 2035.
- The $60,000 per accident figure is shared among everyone hurt in the same crash, not paid to each person.
- Underinsured motorist coverage on your own policy fills part of the gap when the at-fault driver's limit runs out.
- Drivers who were uninsured at the time of the crash cannot recover pain and suffering damages, even when someone else caused it.
- You have two years to file against a private driver and six months to file a claim against a public entity.
Who actually pays after a California crash
The at fault driver's liability insurer pays first, and in most crashes, it is the only payer. California runs an at fault system, so there is no personal injury protection benefit that pays your medical bills regardless of blame.
Beyond that first policy, four other sources show up often enough to be worth checking before settling anything.
- Your own MedPay coverage, if you bought it, pays medical bills up to its limit without regard to fault.
- Your uninsured or underinsured motorist coverage, which steps in when the other driver had nothing or had too little.
- A commercial or employer policy, if the at fault driver was working. Commercial limits are usually several multiples of a personal policy.
- A rideshare policy, which carries a $1 million liability limit while a driver is on an active trip.
A fifth possibility is the vehicle's owner, when that is a different person from the driver. California caps a permissive use owner's liability at $15,000 for one injury and $30,000 for one accident, a figure that was never raised alongside the minimum coverage increase.
California's minimum insurance limits, and what changes in 2035
Since January 1, 2025, the minimum a California driver must carry is $30,000 for injury or death to one person, $60,000 per accident, and $15,000 for property damage. The previous minimums had been 15/30/5 since 1967.
Those minimums go up again on January 1, 2035, to $50,000 per person, $100,000 per accident, and $25,000 for property damage.
The per accident figure is the one that catches people. A $60,000 per accident limit is not $60,000 for each injured person. It is $60,000 divided among everyone hurt in that crash, which means a three-person injury claim against a minimum limits policy is competing for the same money.
What happens when your damages are bigger than the other driver's policy
A liability insurer does not pay past the policy limit. If your documented damages come to $140,000 and the at-fault driver carries the minimum, the liability payment stops at $30,000 and the remaining $110,000 has to come from somewhere else or go uncollected.
Underinsured motorist coverage on your own policy is the usual answer. California defines an underinsured vehicle as one whose liability limits are lower than your UIM limits, and under the uninsured motorist statute, the UIM insurer's exposure is its limit less what the liability insurer already paid.
That subtraction is why UIM disappoints people. If you carry $100,000 in UIM and the at fault driver's insurer pays $30,000; your UIM claim is worth up to $70,000, not $100,000. Carrying UIM at the same limit as the other driver's liability coverage produces nothing at all.
Pursuing a driver's personal assets is possible and rarely productive. Most people with minimum limit policies do not have recoverable assets, and a judgment that cannot be collected is paperwork.
Were you uninsured when the crash happened?
If you were driving your own uninsured vehicle, 주민발의안 213은 비경제적 손해에 대한 배상을 받을 수 없도록 규정하고 있습니다. even when the other driver was entirely at fault. Pain, suffering, physical impairment, disfigurement: all of it is off the table. Medical bills and lost wages still are not.
On a claim where most of the value sits in non-economic damages, which describes most soft tissue claims, this removes the majority of the case.
Three situations fall outside the bar. It does not apply if the at fault driver was convicted of driving under the influence arising from that crash, and it does not apply to passengers, who are not required to insure anything.
The third came from the California Supreme Court. Hodges v. Superior Court held that the bar does not reach a product liability claim against a vehicle manufacturer, because that claim does not arise from the operation or use of the vehicle in the way the statute means.
Check the insurance box in the calculator. An estimate built on coverage you did not have is not an estimate.
Does minor vehicle damage lower an injury claim?
Nothing in California law ties injury damages to repair cost. Damages are measured by the harm to the person, and a bumper that absorbed the impact well is not evidence that a neck did.
In practice, low property damage gets used as an argument anyway, and it is an argument worth preparing for rather than dismissing. Claims involving minor vehicle damage and soft tissue complaints have historically been routed into separate handling programs built around that correlation.
What answers it is the medical record. A documented mechanism of injury, an early diagnosis, consistent treatment, and a physician willing to state the connection carry more weight than photographs of a car do. Speed and damage also correlate loosely at best, since a low-speed rear impact transfers force differently depending on head restraint position, seat design, and whether the occupant saw it coming.
How fault splits the payout in California
California uses pure comparative fault, which means your damages are reduced by your percentage of responsibility, and the claim survives at any percentage. Found 30% at fault on a $100,000 claim and you recover $70,000. Found 80% at fault and you recover $20,000.
No threshold cuts you off. States using modified comparative fault bar recovery entirely once a plaintiff crosses 50% or 51%, and California rejected that approach in 1975.
Fault percentages are negotiated, not assigned by any neutral party during a claim. A police report's opinion about fault carries weight with an adjuster but is not binding, and traffic collision reports are generally inadmissible at trial.
How long you have to file a car injury claim
Two years from the date of the crash, under 민사소송법 제335조 1항. Miss it and the claim is over regardless of how clear the liability was.
Claims against a public entity run on a far shorter clock. If a city bus, a county vehicle, or a dangerous road condition is involved, you must present a written claim to that entity 6개월 이내 before a lawsuit is possible. That deadline catches people who spent the first several months focused on treatment.
Minors get more time, since the two year period generally does not start running until the eighteenth birthday.
Crash injuries in Los Angeles and Orange County
Los Angeles County recorded 58,758 people killed or injured in traffic collisions in 2023, with 12,319 fatal and injury collisions involving speed. Orange County recorded 17,809 killed or injured across the same year, with 4,062 speed related fatal and injury collisions.
Both figures come from the Office of Traffic Safety, which compiles them from the Statewide Integrated Traffic Records System. Neither number says anything about what individual claims settle for, and no California agency publishes settlement data by county.
일반적인 질문들
Is $50,000 a good settlement for a car accident? It depends on two things: what the documented damages are, and how much coverage exists. A $50,000 offer on a claim with $8,000 in paid medical bills and a full recovery is strong. The same offer on a surgical claim against a $100,000 policy is not.
How much of a $30,000 settlement will I get? Subtract the attorney fee, then case costs, then medical liens. The $30,000 figure appears often because it matches California's minimum per person limit, which means it is frequently a policy limits tender rather than a valuation of the claim.
What if the other driver fled? A hit and run is handled through your uninsured motorist coverage. California requires physical contact with the unidentified vehicle for an uninsured motorist claim, so a witness statement describing a car that caused a crash without touching you creates a problem.
Does my own insurance rate go up if I make a claim? Not for a crash where you were not at fault. California prohibits surcharging a policyholder based on a not at-fault accident.
Should I give the other driver's insurer a recorded statement? You are not obligated to. Your own policy generally requires cooperation with your insurer. The other driver's insurer has no such claim on you.
Get a read on your own numbers
The calculator gives you a range. Where your claim falls inside it comes down to what your medical records document about function, whether treatment escalated, and what coverage is available, and those are questions worth putting to someone who reviews these files daily.
DK Law handles back and spinal injury claims throughout California. Call 800-719-9779 for a free consultation or 사례 평가를 요청하세요. No cost unless we recover for you.
내게 필요한 정보 찾기
위치 또는 케이스 유형별로 검색하든, 저희는 여러분이 필요한 곳에 정확히 도착하는 데 도움을 드립니다.
내 주변 지점 찾기
가까운 DK Law 지점을 찾아보세요.

DK Law 전문 분야 찾기
교통사고부터 사망사고까지, DK Law의 주요 전문 분야를 확인해보세요.

DK All The Way
사고 직후부터 보상까지 all the way 함께
상담 예약
교통사고 전문 변호사와 1:1 맞춤 한국어 상담
DK Law에서는 여러분과 함께합니다 -
DK all the way
지금 바로 교통사고 전문 변호사와 무료 상담을 받아 보세요!

교통사고 보상, 시간이 관건입니다!
사고 후 대처가 빠를수록, 교통사고 보상 더 잘 받을 수 있습니다. 사고의 초기 대응이 증거 보존 및 피해자 권리 보호에 큰 도움이 됩니다.
승소하지 않으면 변호사 선임료 $0 | 24시간 상담 가능